


Robinhood’s move is easy to misread if one looks only at the surface. At the surface, the story is attractive: a large retail broker has launched a public, Ethereum-compatible, Arbitrum-based Layer 2; it supports wallets, ETH gas, bridging, tokenized market exposure and DeFi integrations; and it wants to make financial products cheaper, more portable and more globally accessible. That is all broadly true.
The real strategic question sits underneath. Robinhood is building a permissionless financial chain, but the assets that make the chain strategically interesting are not truly permissionless financial objects. They are wrapped claims that remain legally mediated. The chain may be open to deploy on. The token may be transferable across supported wallets. But the economically meaningful instrument still rests on an issuer, a prospectus, a custodian, an authorised participant network, sanctions and KYC controls, jurisdictional exclusions, oracle design, and legal recourse that looks nothing like direct share ownership.

That is the brokerage chain paradox. Robinhood’s opportunity is to hide this complexity well enough that the product feels simple, global and useful. Robinhood’s risk is that users, developers and regulators refuse to ignore the complexity underneath. If users think “tokenized stock” means “stock”, the gap between language and legal reality becomes a product-liability issue. If regulators think the wrapper is clear and fairly disclosed, the structure may scale. If they think the wrapper encourages misunderstanding, scale could stall precisely where the story becomes interesting.
Seen in that light, Robinhood Chain is neither a pure crypto experiment nor a simple extension of the brokerage app. It is an attempt to manufacture a new layer in between: a consumer-facing financial stack where the interface feels straightforward but the mechanics underneath are deeply structured, heavily controlled and jurisdiction-specific. That is commercially plausible. It is also inherently fragile. No part of the strategy works if Robinhood cannot maintain the illusion of simplicity without overstating what the user actually owns.
Robinhood Today and the Super-App Ambition
Robinhood is not launching Robinhood Chain as a defensive manoeuvre. The company is doing so from a position of unusual operating strength for a broker that, only a few years ago, was still treated by many investors as a cyclical retail-trading platform.
Robinhood (NASDAQ: HOOD) is scheduled to release its Q2 2026 financial results on Wednesday, July 29, 2026, after the market closes.
In Q1 2026, it delivered $1.07 billion of net revenue, $623 million of transaction-based revenue, $359 million of net interest revenue, $346 million of net income and $534 million of adjusted EBITDA. Total platform assets reached $307 billion, funded customers 27.4 million, ARPU $157 and Gold subscribers 4.3 million.
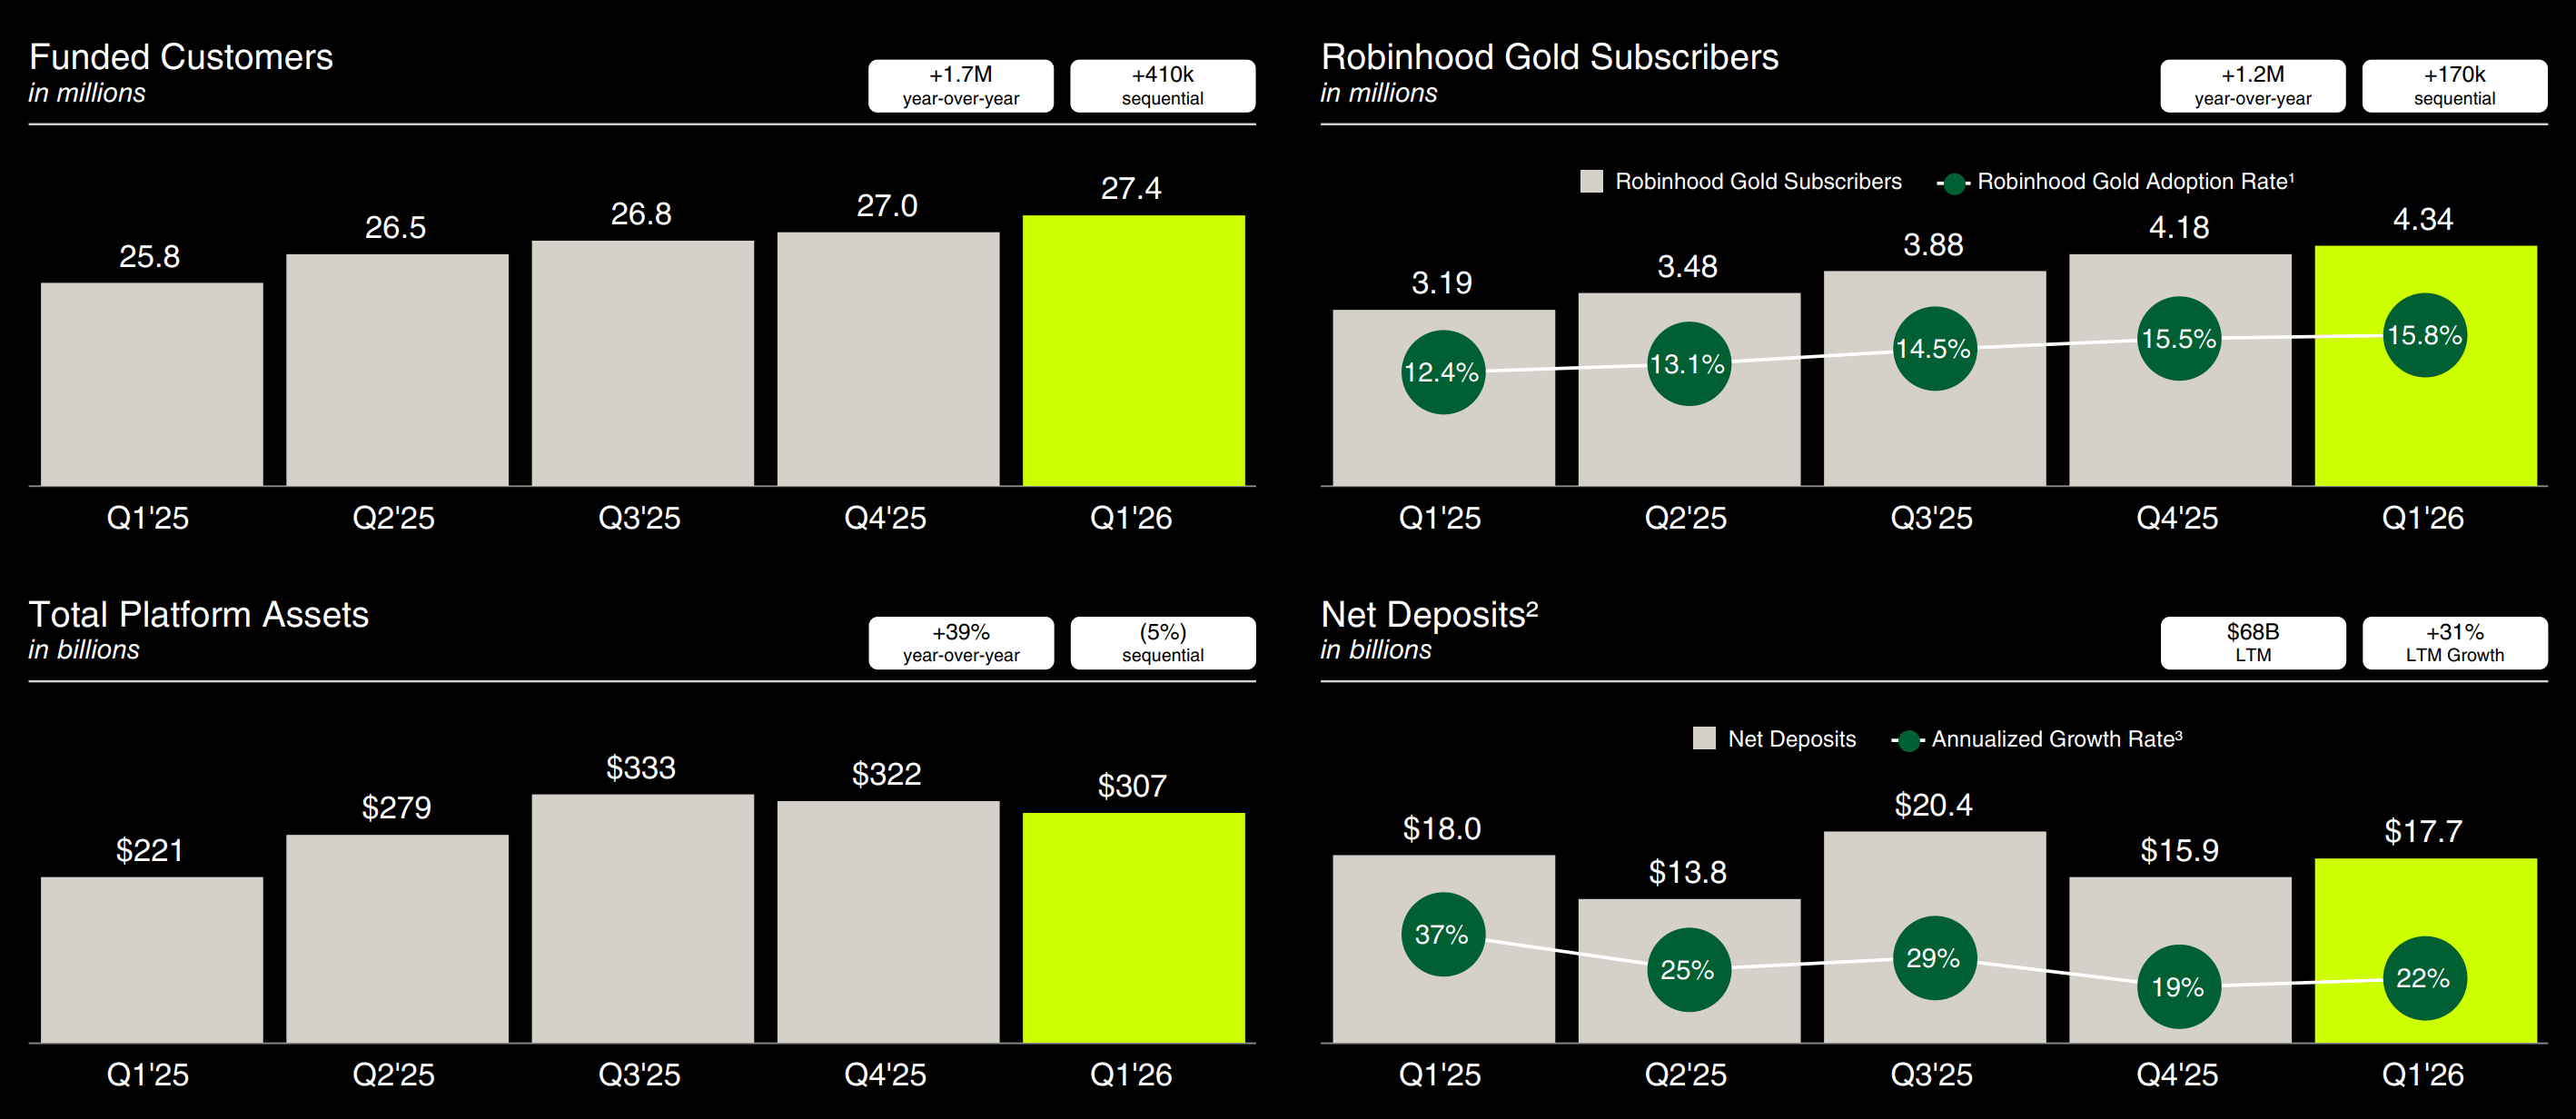
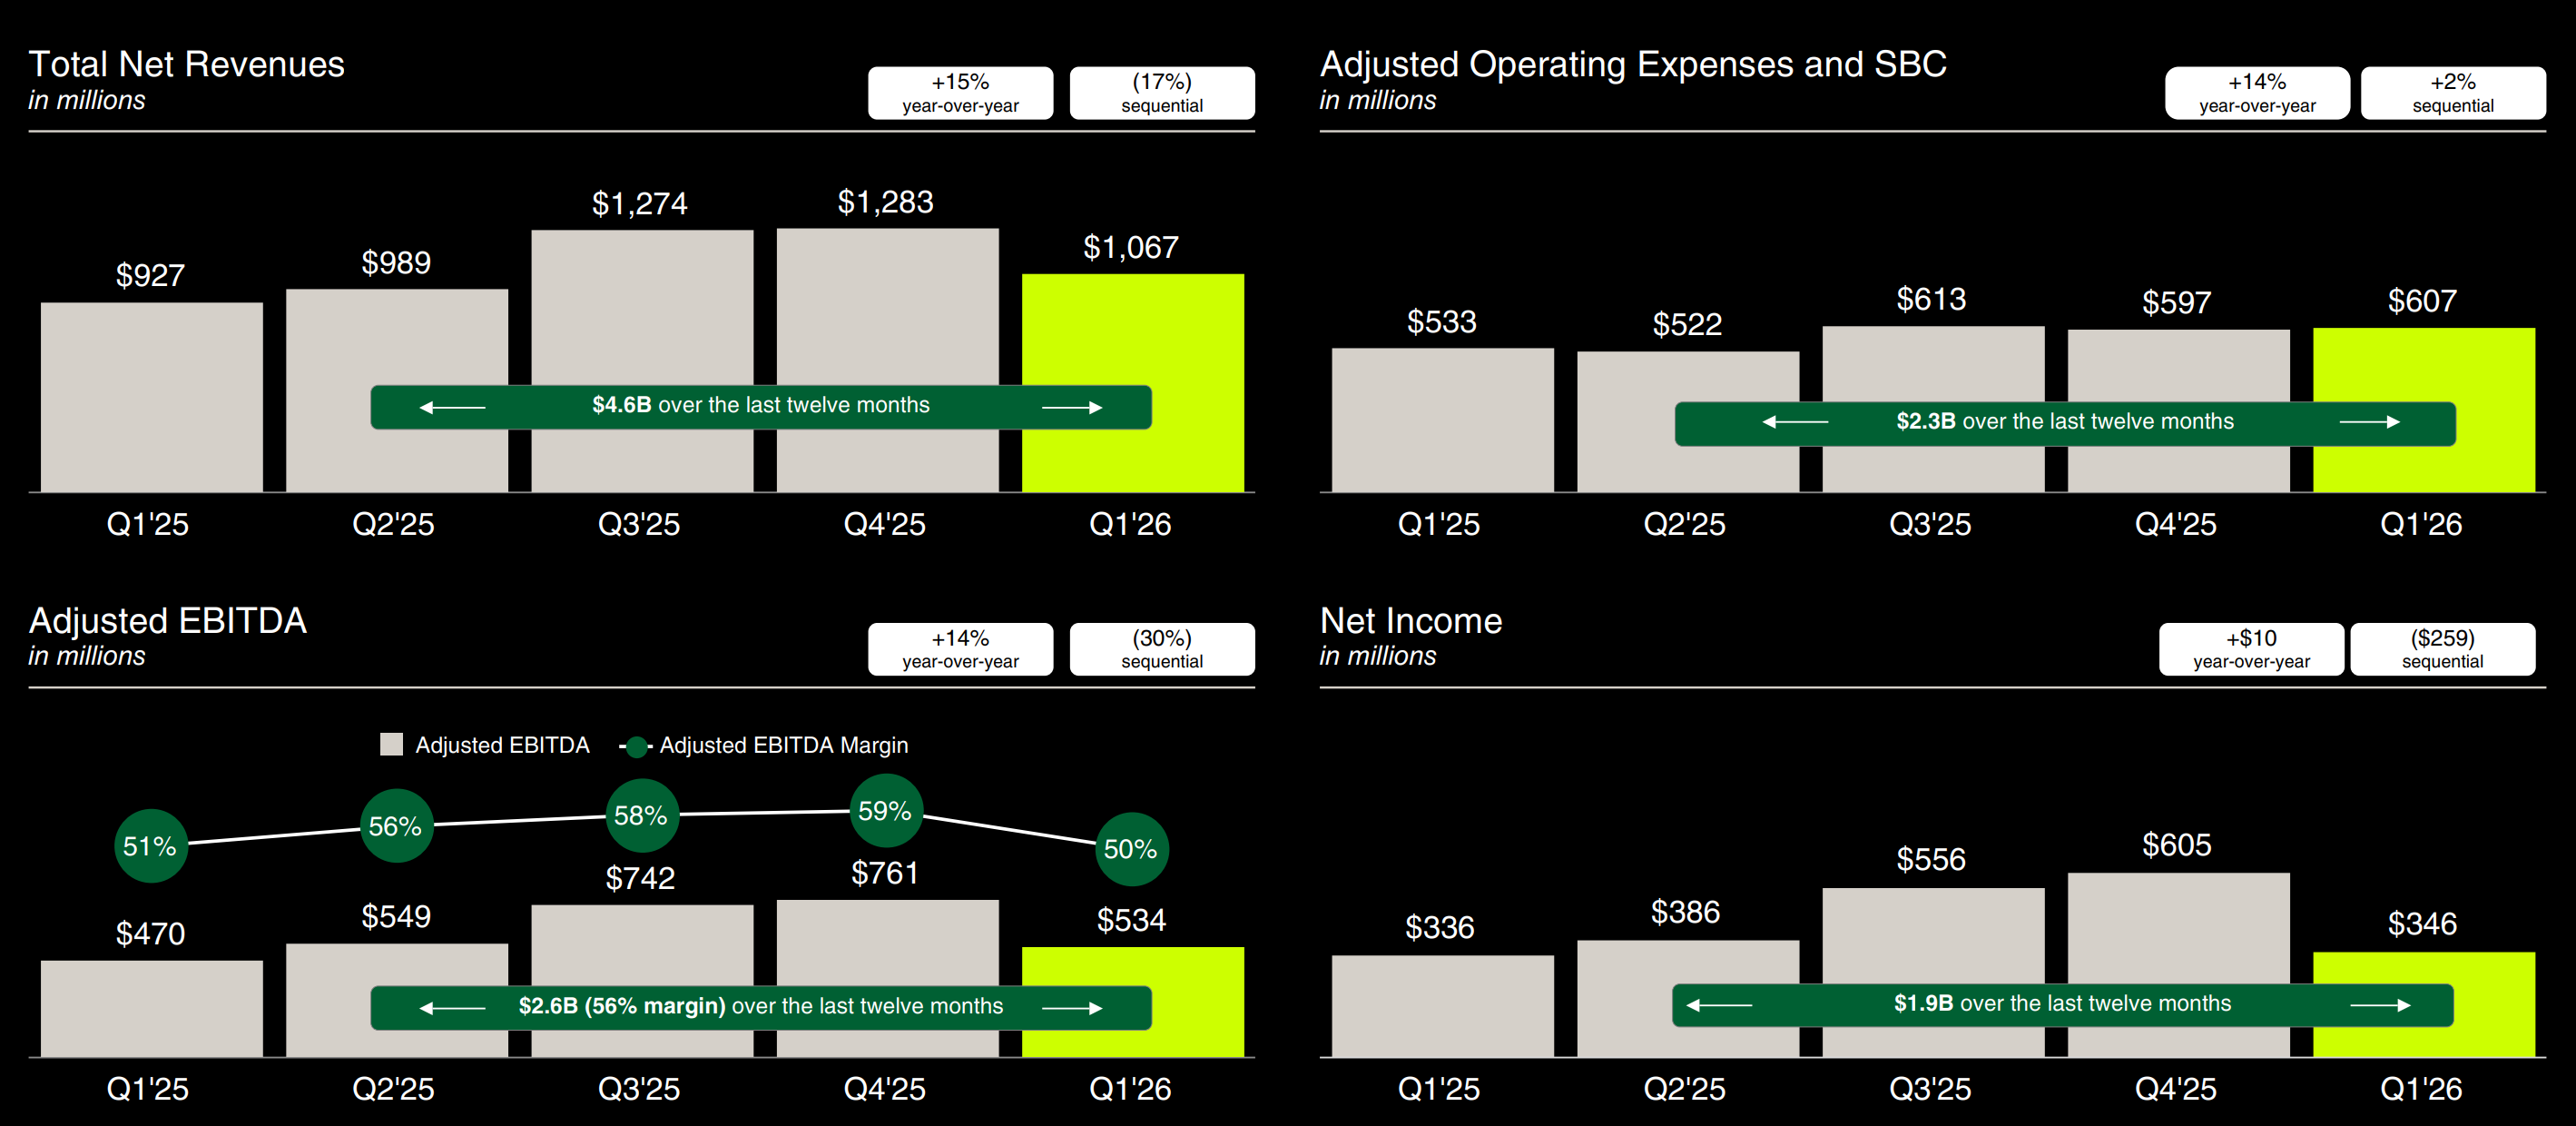
The revenue mix matters because it shows where the business is actually monetising today. Options generated $260 million of transaction-based revenue in Q1 2026, equities $82 million, event contracts $104 million, other transaction revenue $43 million and crypto $134 million. The standout growth line was event contracts, which rose from $3 million in the prior-year quarter to $104 million, while crypto revenue fell from $252 million to $134 million. Robinhood Chain is therefore being launched at a time when the company’s earnings are still primarily driven by active retail trading, margin-rich products and balance-sheet monetisation, not by any existing onchain business line.
This distinction is important for both strategic and valuation purposes. Robinhood Chain is not rescuing the business. It is trying to create a new surface above a business that is already working. That makes the initiative more credible, because the company can afford to experiment. It also makes the initiative easier to overstate, because the existing earnings engine remains rooted in mature brokerage economics.
The rest of the balance-sheet and engagement picture points in the same direction. Robinhood disclosed a $17.0 billion margin book, $16.7 billion of cash and deposits, $27.4 billion of retirement assets under custody and $66 billion of crypto notional volume in Q1 2026, including $42 billion from Bitstamp and $24 billion from the Robinhood app. That last figure is especially relevant. Bitstamp is already making Robinhood’s crypto footprint look more like infrastructure and less like an isolated retail trading feature.
From brokerage app to financial super-app
Robinhood’s strategic logic now looks more coherent than it did when the company first began adding disparate products around its core brokerage. In Q1 2026 and subsequent public materials, the company was no longer simply describing product expansion. It was sketching a fuller operating model: brokerage, options, futures, event contracts, banking, Gold, retirement, crypto, wallet, private-markets access, AI tools, global licensing, tokenized assets and DeFi-linked yield. Management’s language about building a “global financial ecosystem” is not just corporate flourish. It is an attempt to explain how the various layers fit together.
That broader stack now includes several pieces that would have looked disconnected in isolation. Robinhood Banking and higher cash engagement matter because they deepen deposit and balance relationships. Robinhood Gold matters because it improves subscription attachment and supports the premium-wrapper model. Retirement matters because it extends the lifecycle of assets and reduces pure trading cyclicality. Futures and event contracts matter because they increase engagement and monetisation intensity. Crypto matters because it provides 24/7 markets, self-custody rails and global funding flexibility. Bitstamp matters because it expands institutional and international reach. The wallet matters because it gives Robinhood a credible non-custodial interface. Robinhood Chain matters because it offers a programmable settlement layer where all of those financial behaviours can, in principle, start to converge.
The company’s international vector reinforces the same point. Robinhood has expanded into Canada via WonderFi, disclosed Singapore regulatory progress, and described UK crypto plans. Those steps matter not simply as new territories, but because they create a test bed for products that do not fit neatly inside the U.S. retail brokerage rule set. tokenized wrappers and wallet-native products are easier to introduce at the edge of the group than at the regulated core of the U.S. app.
The strategic sentence, then, is simple: Robinhood Chain matters because it may let Robinhood extend its consumer distribution advantage into programmable finance without turning the core U.S. brokerage into a crypto-native venue overnight. That is why the chain should be read as infrastructure strategy, not launch collateral.
What Robinhood Chain Actually Is
Robinhood Chain’s documentation describes it as an Arbitrum Layer 2 chain built on Ethereum, using Ethereum blobs for data availability and ETH as the native gas token. Robinhood Wallet supports it natively, and other EVM wallets can add it manually. Assets can be moved onto the chain using the canonical Arbitrum bridge or partner routes. Public materials also emphasise that the chain is open and permissionless, EVM-compatible and designed for tokenized real-world assets.
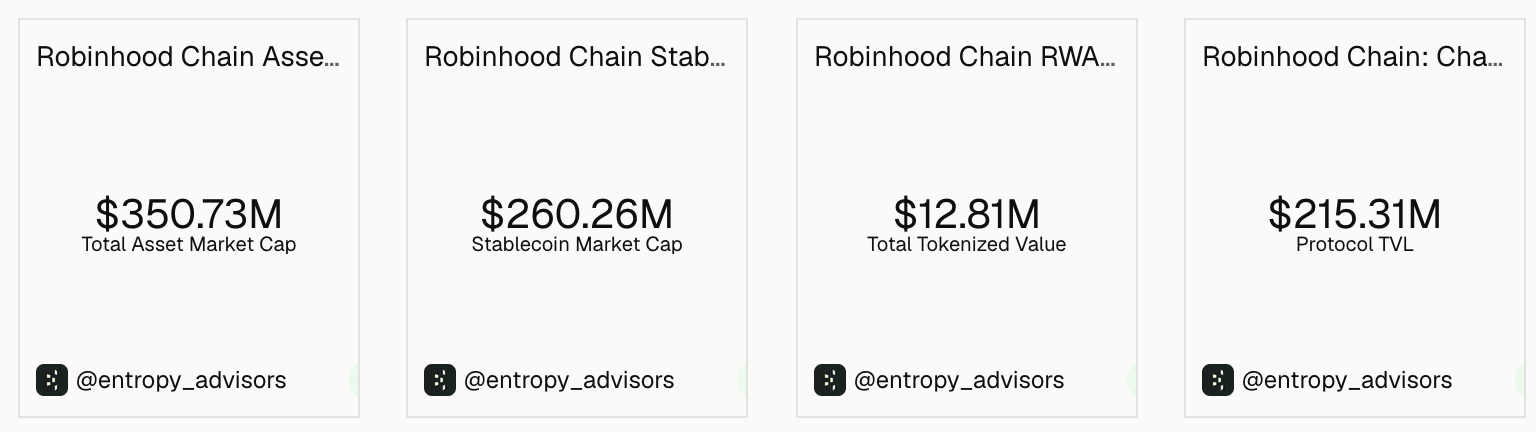
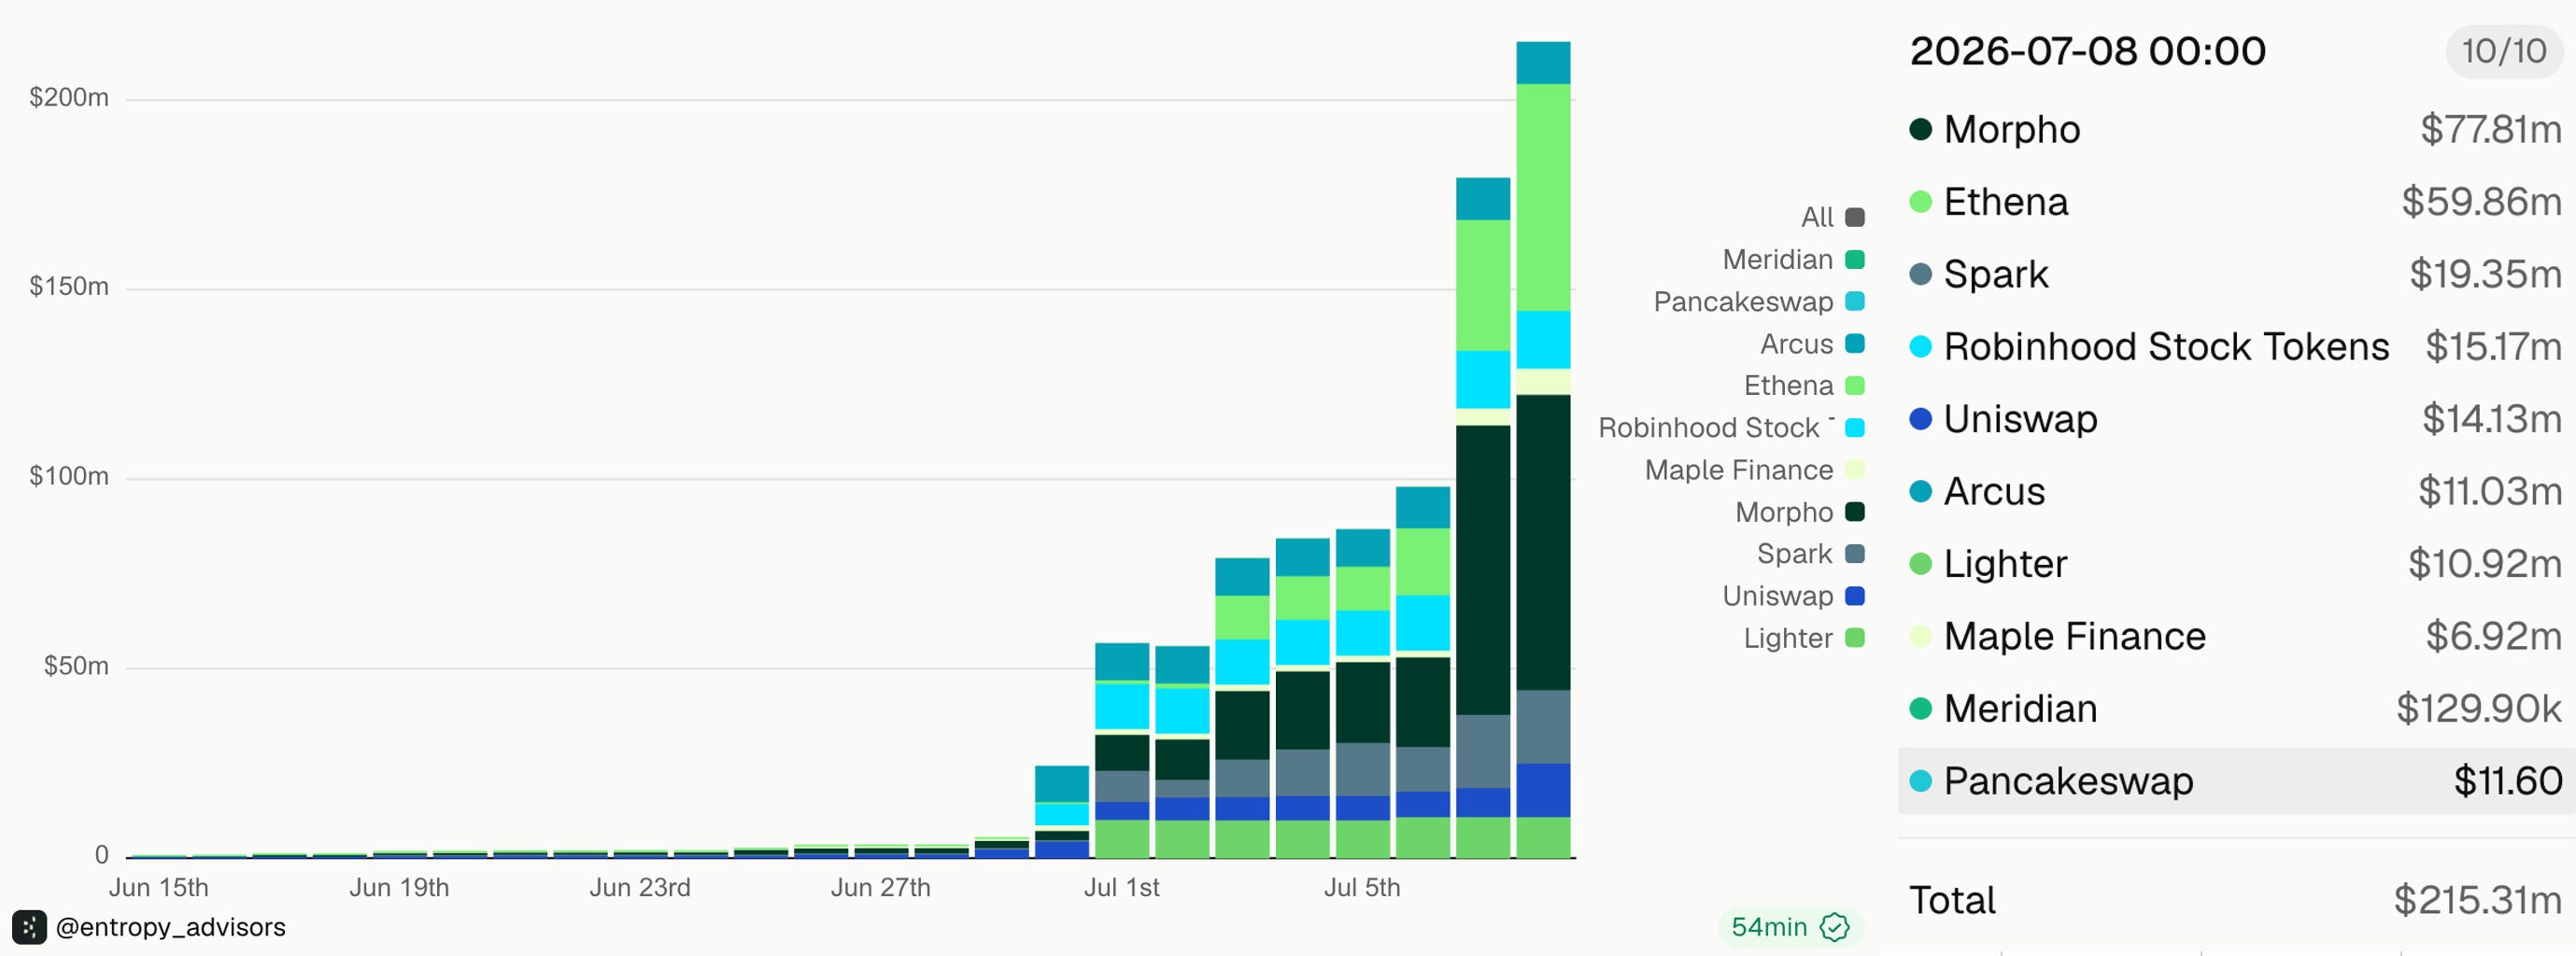
Robinhood’s July 2026 launch materials say the chain is built using the Arbitrum platform “to institutional standards” and name Uniswap as a day-one AMM and Pleiades as a proprietary AMM / prop-trading venue. Robinhood’s technical documentation adds that Stock Tokens are standard ERC-20s and that each token has a Chainlink price feed, with corporate actions reflected through an onchain multiplier rather than a rebasing balance change.
The public docs, however, are not equally complete across all infrastructure questions. We found clear documentation on connectivity, gas, bridging, token format and oracle design, but less explicit public explanation of sequencing decentralisation, governance path, fault-proof status, or the precise current production roles of every named infrastructure partner. That does not mean the system is weak; it means some institutional-grade diligence questions still require more disclosure than the public docs currently provide.
The main takeaway is straightforward. Robinhood Chain is real, but still early. It has infrastructure, partners and live products attached to it. What it does not yet have is proof of durable liquidity, broad developer adoption, seamless regulatory portability or material revenue contribution. The distinction matters. A public mainnet and a few live products are enough to make the strategy serious. They are not enough to make it proven.
Stock Tokens and the Legal Reality of Onchain Equities
The most important sentence in this paper is also the simplest: Robinhood’s Stock Tokens should not be described as stocks onchain. They are tokenized economic exposure to securities through legal wrappers.
Robinhood’s onchain Stock Tokens are described in public materials and prospectus documents as tokenized debt securities issued by Robinhood Assets Jersey Limited. They provide economic exposure to the referenced stock or ETF, but users do not obtain direct legal title to the underlying securities, beneficial ownership of those shares or ordinary shareholder rights such as voting. The product documentation is explicit on this point, and the prospectus framework is clearer than much of the marketing shorthand around “stock tokens” would suggest.
Robinhood Europe’s earlier “Classic Stock Tokens” are legally different again. Those products are described as derivative contracts between the user and Robinhood Europe, UAB. They are not transferable to external wallets and can only be entered into or terminated through the Robinhood Europe platform. The legal perimeter there is even less ambiguous: the customer is dealing with a derivative exposure, not a tokenized bearer claim.
The newer onchain product is more radical in distribution, but conservative in legal architecture. That is precisely why it may work. The token can behave like a crypto asset at the interface layer: transferred onchain, held in compatible wallets, referenced in DeFi and priced by oracles. But the claim underneath stays conservative: a Jersey-issued, prospectus-governed, secured, limited-recourse debt security referenced to underlying shares. Robinhood is not dismantling securities law. It is packaging around it.
That legal packaging has consequences. “Backed 1:1” does not mean “you own the share”. The token holder’s exposure depends on the issuer, authorised participants, custody arrangements, collateral framework, secondary-market liquidity, jurisdictional permissions and redemption mechanics. The base prospectus states that only authorised participants subscribe directly from the issuer, while ordinary investors generally acquire exposure in the secondary market. Direct redemption by ordinary investors exists only under specified conditions; otherwise, investors are expected to sell or redeem through market intermediaries. Redemption is cash-based and conditional, not equivalent to pulling a share certificate out of a vault.
The structure also depends on named service providers and legal control points. The documents reviewed in the underlying research identify Robinhood Assets Jersey Limited as issuer and tokenizer, Bitstamp Global Ltd. as authorised offeror in the relevant terms reviewed, and Alpaca Securities LLC as custodian and broker for the referenced series. Those roles matter because tokenized exposure that aspires to be globally portable is, in practice, still held together by highly traditional financial plumbing.
Even the asset-backing story is more complex than the phrase suggests. Robinhood’s materials say each token is backed 1:1 by the underlying equity. The prospectus framework describes segregated accounts for each series, but also permits securities lending. During the life of a securities-loan transaction, the issuer’s economic exposure runs through collateral and contractual rights, rather than through untouched shares sitting inertly in custody. In stressed conditions, that difference can matter. It introduces borrower, collateral, operational and recovery-value risks that are foreign to the simple intuition a retail user may draw from the product name.
Corporate actions and dividends are similarly mediated. Robinhood’s materials explain that dividends are handled through a multiplier mechanism that adjusts the token’s reference economics, rather than by giving users direct shareholder distributions. The prospectus also flags withholding and section 871(m) considerations around dividend equivalents. Again, this does not make the product defective. It makes the product structured. Users should be buying that structure with open eyes.
Transferability is real but not absolute. Robinhood says onchain Stock Tokens can be held and transferred on supported blockchains and compatible wallets. At the same time, the documentation permits pauses, freezes and restrictions in certain circumstances, and purchases or redemptions remain subject to KYC, AML, sanctions compliance and jurisdictional exclusions. This is closer to a programmable, wrapped, conditional product than to an unrestricted bearer instrument.
The commercial conclusion is blunt. The product is radical in distribution but conservative in legal architecture. That combination is not a flaw. It is probably the only viable route to market. But it also means Stock Tokens should be valued as a legal and market-structure experiment in making economic exposure portable, not as an onchain substitute for actual share ownership.
Digital Assets as Infrastructure, Not Just Trading Revenue
Robinhood’s digital-asset strategy is now too broad to fit inside the old frame of “crypto trading revenue”. Crypto still matters as a revenue line, but it increasingly matters as infrastructure. That shift is the deeper significance of Robinhood Chain.
Crypto trading revenue remains meaningful but no longer tells the full story. In Q1 2026, Robinhood generated $134 million of crypto transaction revenue, down materially from the prior-year quarter, even as total crypto notional volume reached $66 billion. Of that notional volume, $42 billion came through Bitstamp and $24 billion through the Robinhood app. In other words, Robinhood’s digital-asset footprint is already broader than its consumer crypto tab.
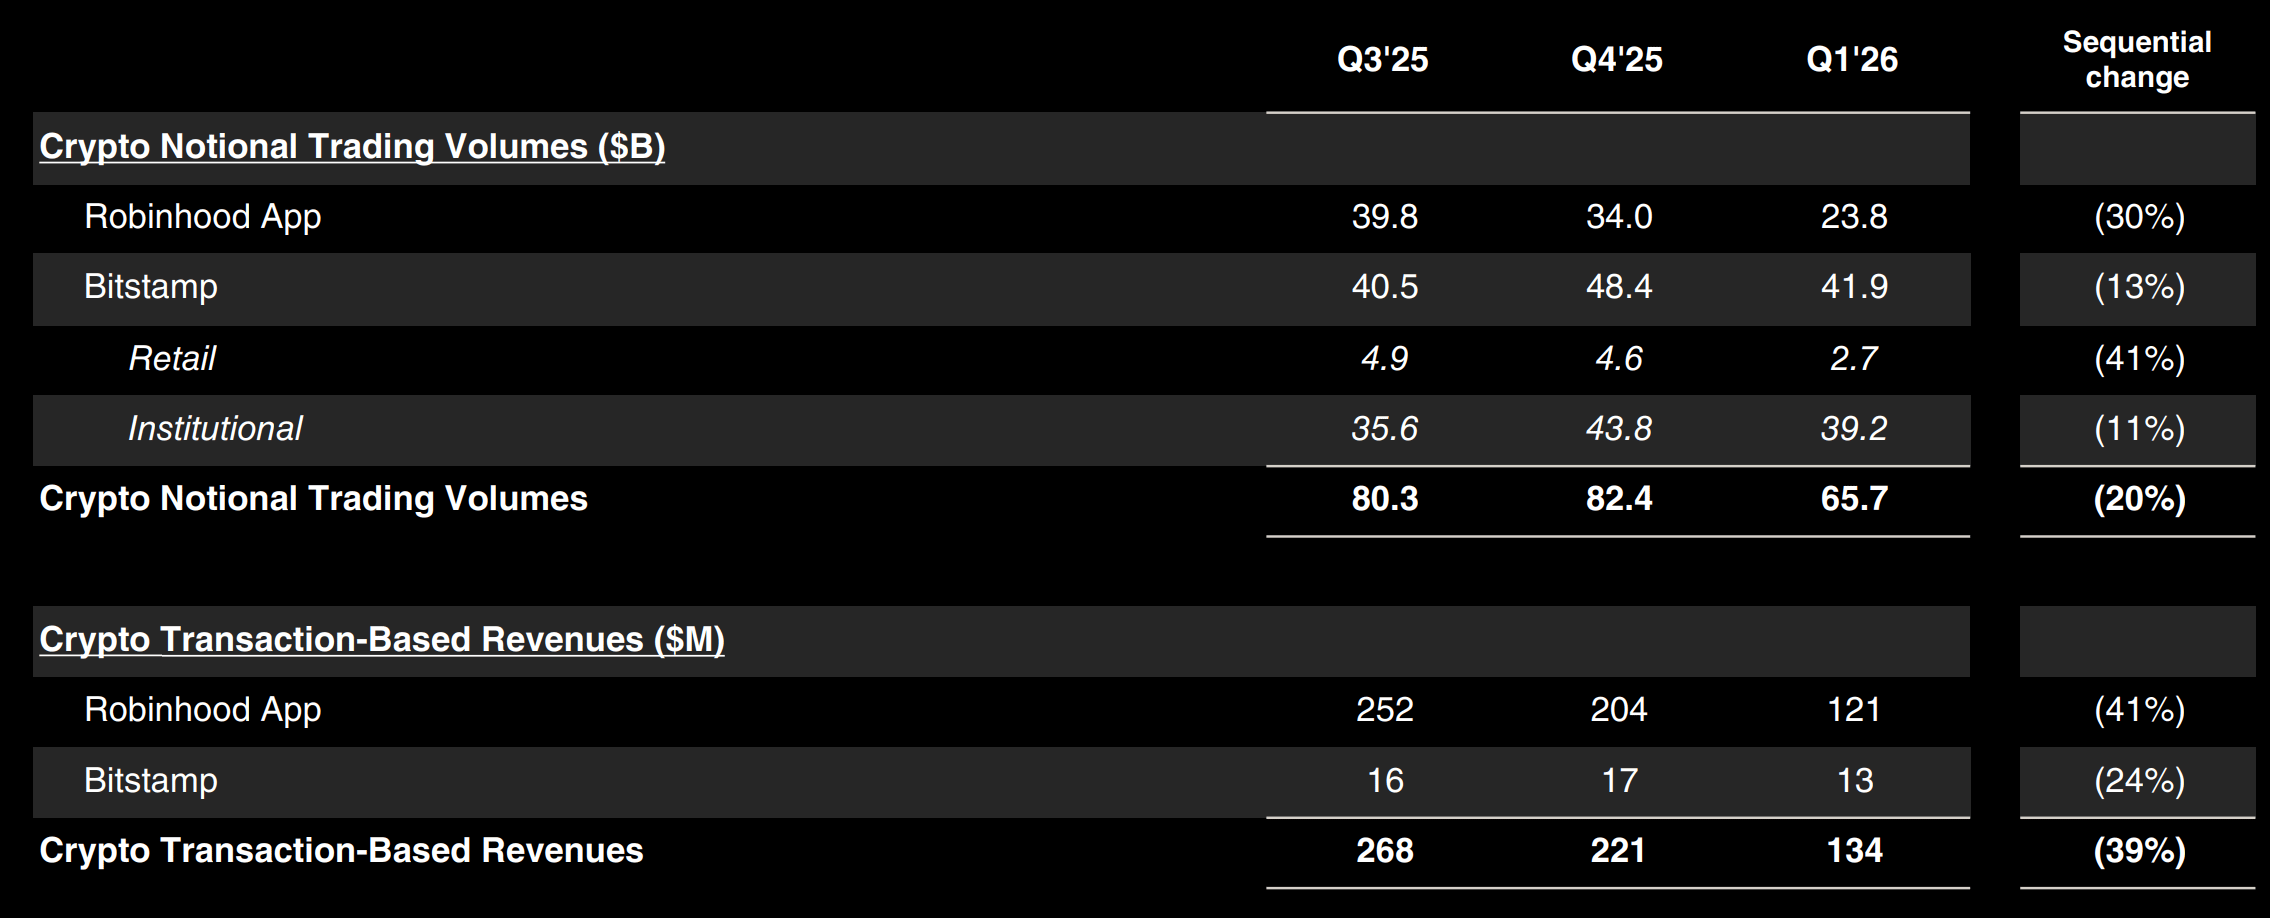
Bitstamp is central here. Robinhood closed the Bitstamp acquisition in June 2025 for approximately $200 million in cash and explicitly framed the deal around global exchange capability, institutional customers, white-label infrastructure, staking, institutional lending and broader licensing coverage. By later filings, Robinhood was already describing Bitstamp as expanding the institutional side of the business into services such as on-exchange lending, off-exchange settlement, post-trade settlement and institutional perpetual futures. That is not what a company says if it still thinks of crypto as a retail side pocket.
Robinhood Earn makes the same point from the consumer side. Public materials describe a simple flow: the user buys USDG on Robinhood Crypto, moves it into a self-custody wallet and lends it via Morpho. Robinhood is careful to disclose that the wallet is non-custodial and that withdrawal timing depends on vault liquidity. Morpho, for its part, describes Robinhood Earn as a progressive rollout for eligible U.S. users. This is not just adding yield to a cash balance. It is teaching the Robinhood user base that DeFi can sit behind the interface without demanding crypto-native behaviour from the customer.
The stablecoin angle matters because it is likely to be more durable than any single speculative trading cycle. If Robinhood can turn stablecoin balances into invisible funding rails, it gets a portable, programmable financing layer for wallet-native activity, international flows and future collateral use cases. In that model, the stablecoin is not the product. It is the settlement medium beneath the product. That is a more strategically important role.
Robinhood Wallet is the user-facing bridge into this stack. Support materials show the wallet already spans multiple major chains and now includes Robinhood Chain itself. That matters because wallet strategy is where brokerage distribution and crypto infrastructure meet. A broker can custody. A wallet can compose. Robinhood increasingly wants both in the same customer relationship.
Why Lighter matters
Lighter is one of the clearest examples of Robinhood’s infrastructure posture. Lighter gives Robinhood access to advanced onchain trading design without requiring Robinhood to build a crypto-native perps exchange from zero. Public materials describe Lighter as a custom zero-knowledge rollup with proofs of order matching and liquidations, price-time-priority execution and an escape-hatch design if certain operations are not processed in time. Robinhood Wallet materials, in turn, describe perpetual futures inside the wallet, including liquidation mechanics and funding dynamics, with the underlying decentralised protocol handling liquidations.
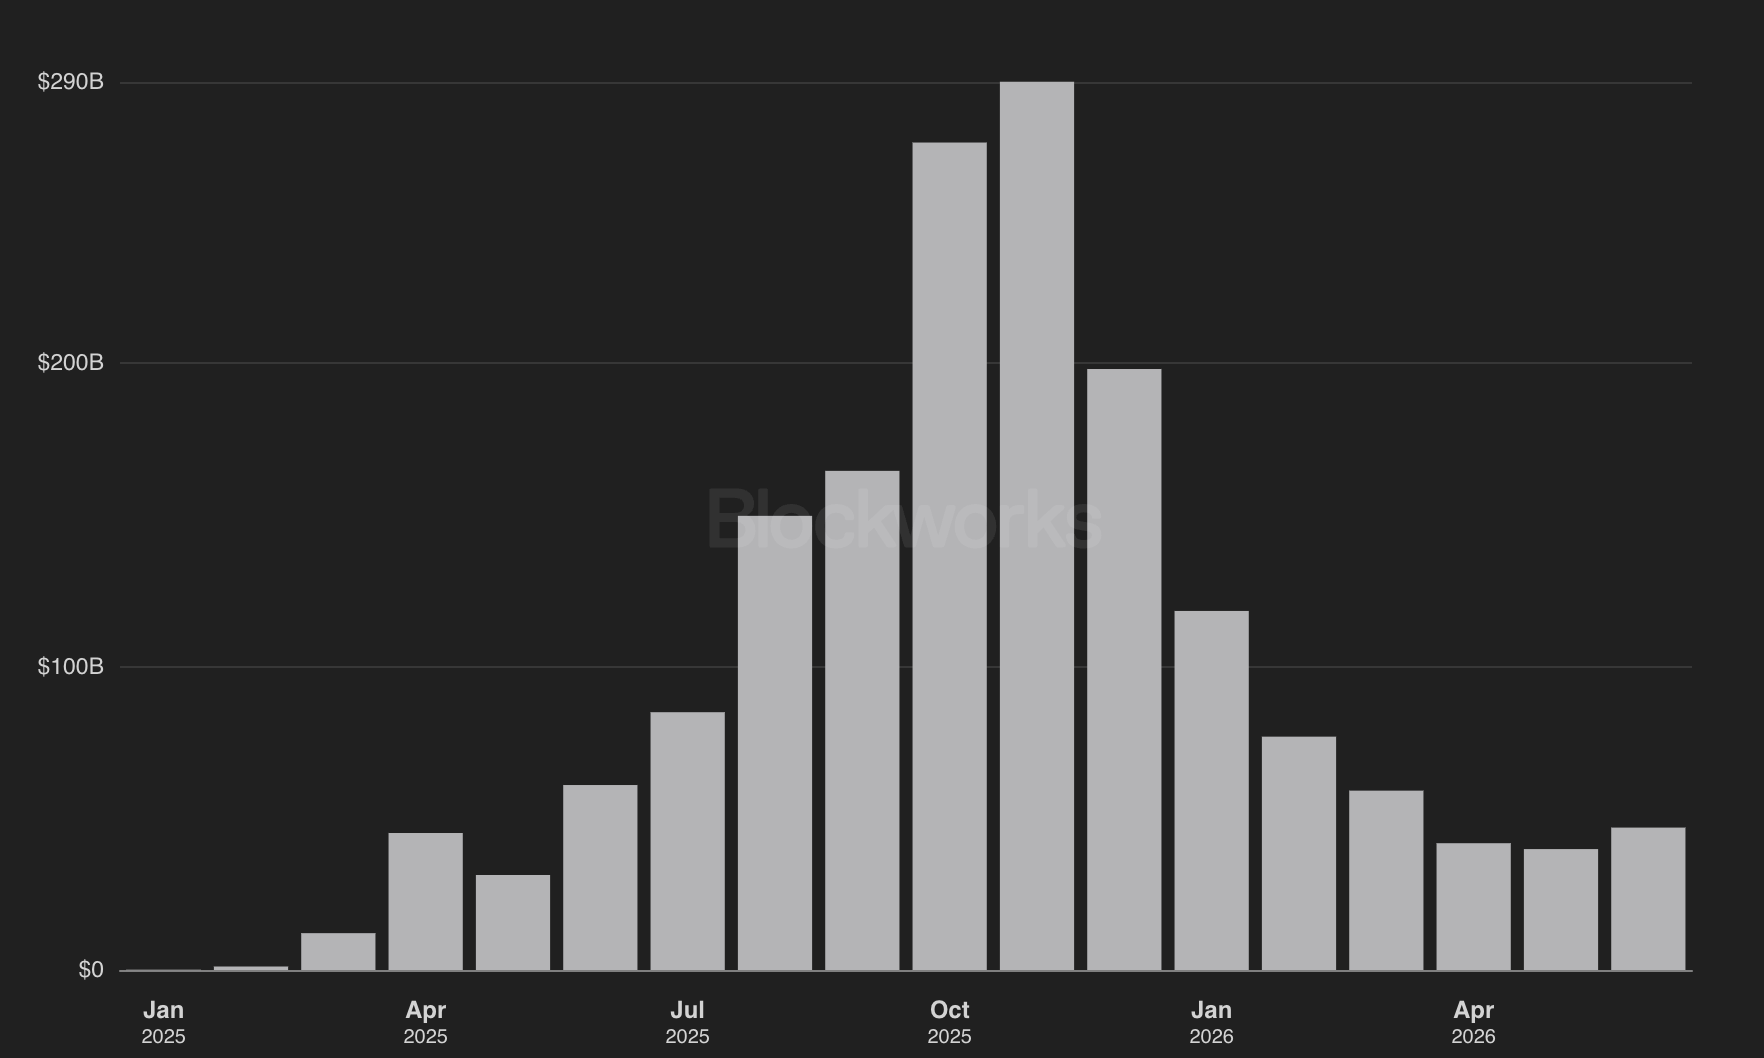
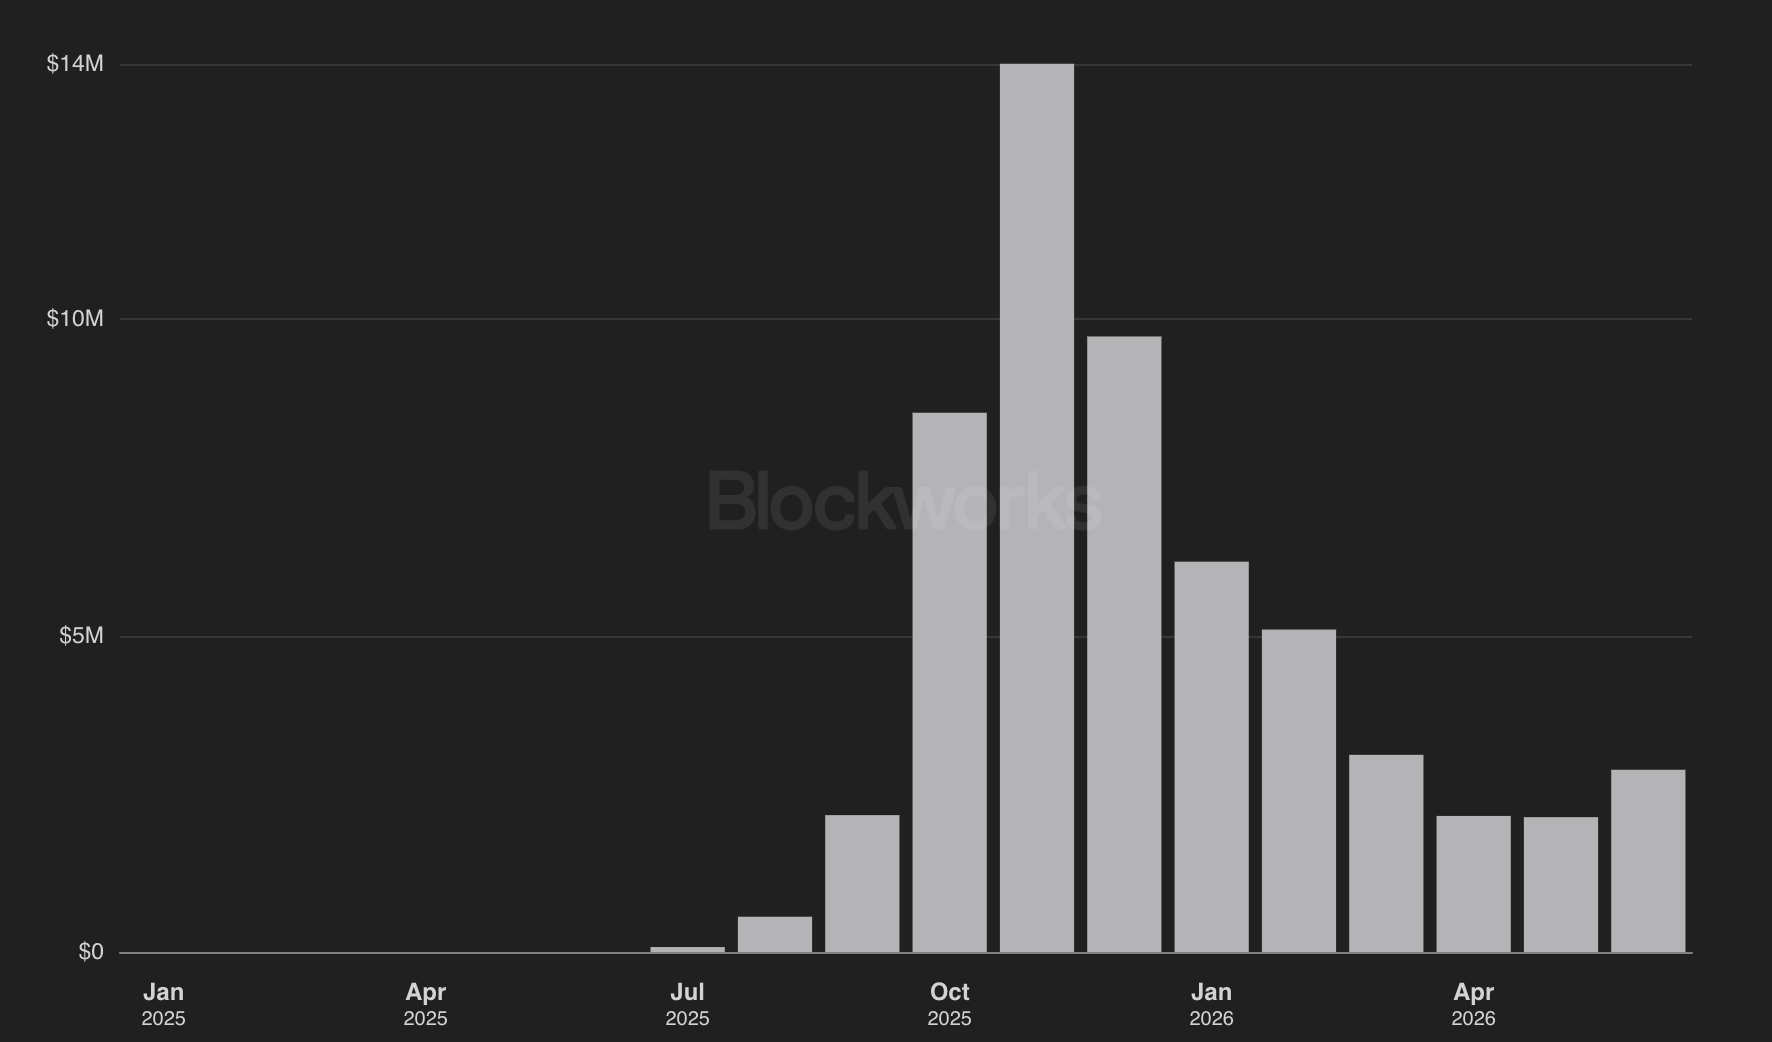
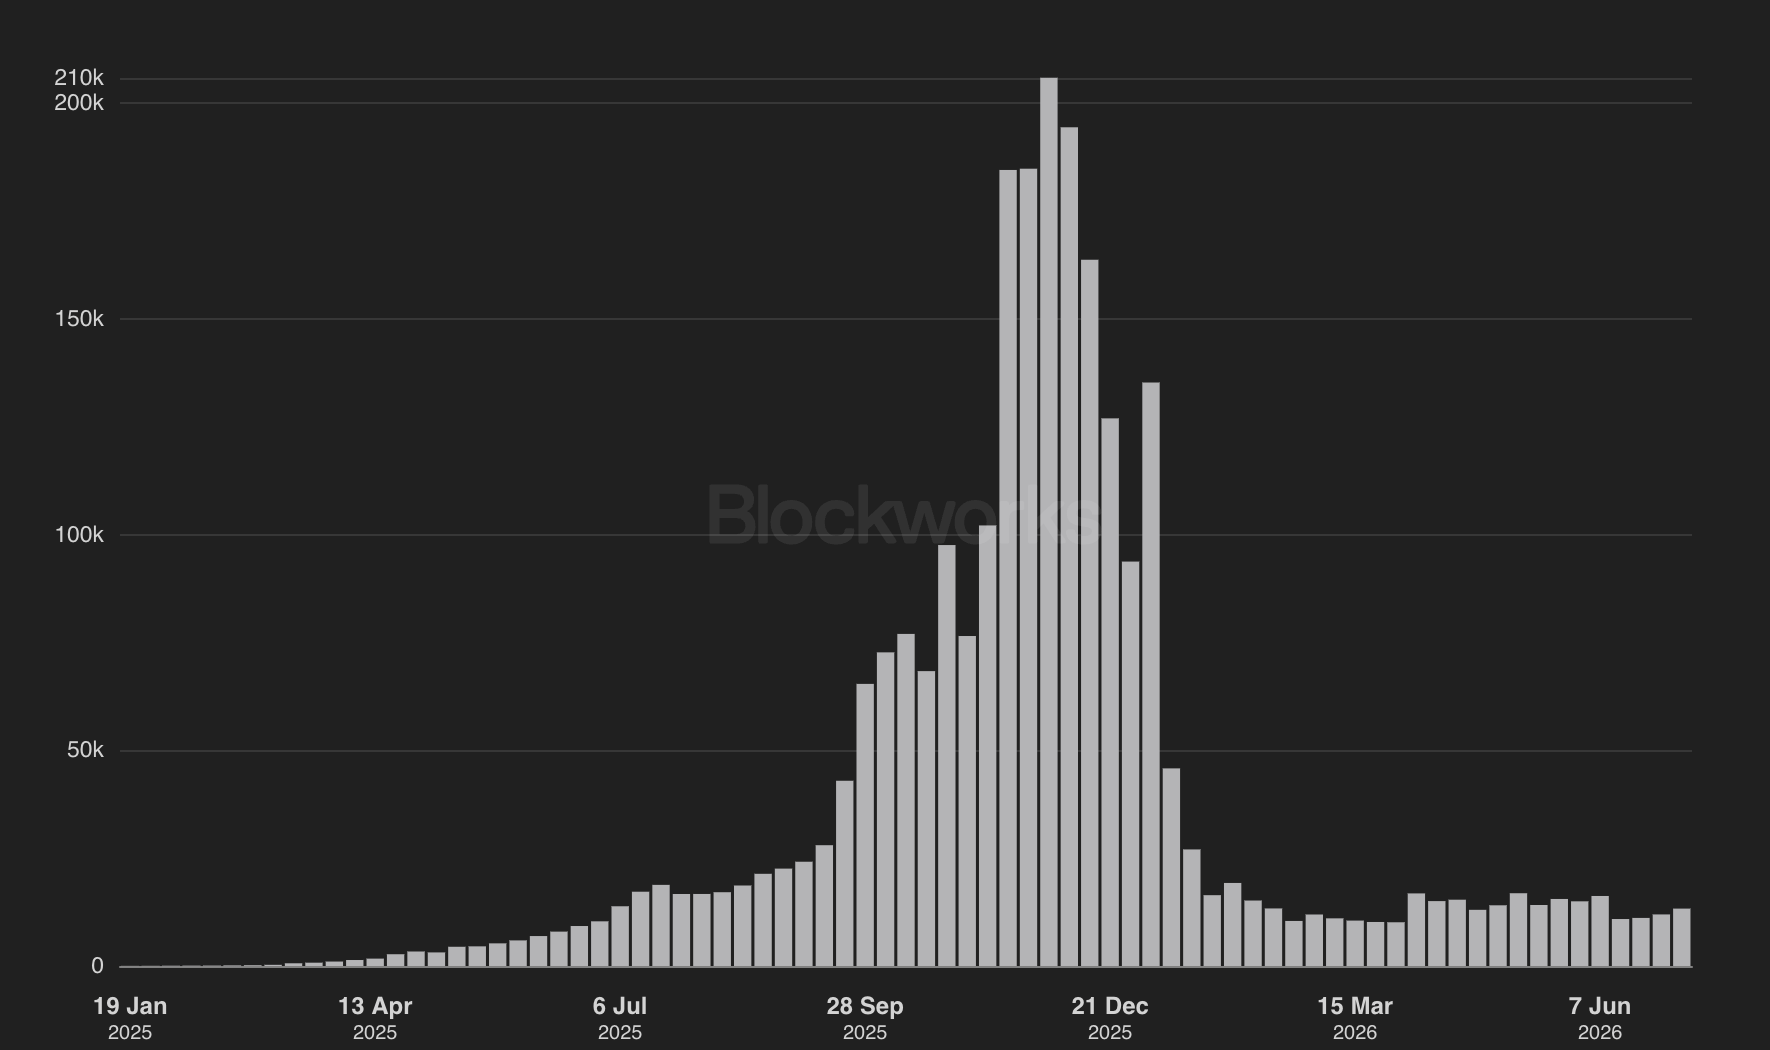
That is strategically useful for several reasons. It enlarges the wallet’s engagement surface. It lets Robinhood test high-frequency, high-engagement trading demand in a self-custody setting. It reduces time-to-market. And it gives Robinhood exposure to the economics and user behaviour of global, always-on trading without moving the full burden into the regulated U.S. broker-dealer stack.
But Lighter also sharpens the brand challenge. Perpetual futures bring leverage, liquidations, incentive-sensitive liquidity and retail-loss risk closer to the Robinhood ecosystem. Lighter’s own documentation makes clear that RWA markets trade around the clock and use margin mechanics. That may be commercially attractive. It is also precisely the sort of product layer that can create political, regulatory and reputational friction for a mass-market broker.
The right conclusion is therefore narrower than the market may want. Lighter is not proof that Robinhood can own perps economics the way Hyperliquid does. It is proof that Robinhood can plug crypto-native trading infrastructure into its consumer wallet funnel. That is strategically meaningful. It is not the same thing as owning the venue.
This is a part of the insights4vc report.
Sources
Partner Highlight
At insights4vc, we pay attention to teams that are not just shipping products, but shaping categories.
Moto is one of them. The company is building a premium card experience positioned as an alternative to traditional incumbents such as Amex, combining a high-end user interface with more modern financial infrastructure.
Moto is currently expanding access to a limited testing group. If you would like to test the product please contact us at: office@insights4.vc
Cover Artwork
The Stone Bridge
Jan van der Heyden c. 1637
Risk Disclaimer:
insights4.vc and its newsletter provide research and information for educational purposes only and should not be taken as any form of professional advice. We do not advocate for any investment actions, including buying, selling, or holding digital assets.
The content reflects only the writer’s views and not financial advice. Please conduct your own due diligence before engaging with digital assets or related technologies, as they carry high risks and values can fluctuate significantly.
The most important sentence in this piece is the one most readers will skip. "Users do not obtain direct legal title to the underlying securities." Everything else follows from that. The token is an ERC-20 on an Arbitrum L2. The claim underneath it is a Jersey-issued, prospectus-governed, limited-recourse debt security with counterparty, custody, and recovery risk identical to structured finance.
So the decentralisation sits at the interface. The legal reality underneath is as centralised as anything on Wall Street. That's not a flaw. It's probably the only structure a regulator would approve. But it means the product's actual risk profile has almost nothing in common with what the word "token" implies to a retail user who came in through a wallet.
The securities lending disclosure is the quiet part. Backing is described as 1:1. But during an active lending transaction, that backing runs through collateral and contractual rights, not through untouched shares in custody. In calm markets, nobody notices the difference. In stressed markets, it's the only thing that matters.